COMMUNITY BANK BUSINESS PLAN
I. Executive Summary
Company Description
Hearthstone Community Bank draws its name from the idea of local roots and home stability; hearthstone evokes neighborhood trust and homeownership. We operate in the retail and commercial banking sector, offering residential mortgages, small-business loans, deposit accounts, cash management, and digital banking tools. We combine local credit decision-making with modern underwriting and online services to deliver relationship-driven lending at scale. One-line: local capital, local decisions, modern delivery.
We target middle-income homeowners, first-time buyers, and small businesses in our metropolitan region seeking faster decisions and personalized service than national chains provide. Short-term goals: open operations in Q2 2026, reach $150M in deposits, and originate $80M in loans year one. Long-term goals: 5% market share in targeted zip codes, 12% ROAE, and sustained portfolio growth tied to community reinvestment. One-line: profitability tied to local prosperity.
Problem
Local residents and small business owners lack a responsive financial partner, which reduces access to capital and personalized guidance and slows community growth. National banking chains use standardized credit models and remote decision-making that overlook local cash-flow patterns, seasonal revenue, nontraditional collateral, and neighborhood credit histories.
Consequences: delayed funding decisions, lower loan approval rates for atypical cash flows, limited homeownership counseling flexibility, and rigid loan covenants that constrain business expansion and local hiring—creating a persistent gap in community-focused banking services.
Solution
Local communities face limited access to capital and impersonal service from large national banks. Our community bank pairs a secure digital platform for everyday banking with in-branch, locally made lending decisions and personal consultations to serve families and small businesses more effectively.
One-liner: Combine tech convenience with local underwriting and relationship banking to unlock capital for community growth.
Mission Statement
Our mission is to fuel local ambitions by providing personalized, responsive, and modern banking that reinvests deposits back into neighborhood businesses and homes; we measure success by visible community growth. We operate with rigorous regulatory compliance and deep, personal relationship banking to be the region’s most trusted financial partner. We commit to creating a sustained cycle of prosperity where our stability is defined by the economic well‑being of our neighbors.
Key Success Factors
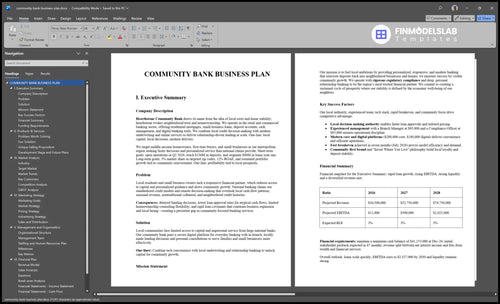
Our local authority, experienced team, tech stack, rapid breakeven, and community focus drive competitive advantage.
-
Local decision-making authority enables faster loan approvals and tailored pricing.
-
Experienced management with a Branch Manager at $95,000 and a Compliance Officer at $85,000 ensures operational discipline.
-
Modern core and digital platforms ($280,000 core; $180,000 digital) deliver convenience and efficient operations.
-
Fast breakeven achieved in seven months (July 2026) proves model efficiency and demand.
-
Community-first brand and "Invest Where You Live" philosophy build local loyalty and deposit stability.
Financial Summary
Financial snapshot for the Executive Summary: rapid loan growth, rising EBITDA, strong liquidity and a diversified revenue mix.
Ratio |
2026 |
2027 |
2028 |
Projected Revenue |
$34,500,000 |
$52,750,000 |
$74,750,000 |
Projected EBITDA |
$11,000 |
$590,000 |
$1,025,000 |
Expected ROI |
3% |
3% |
3% |
Financial requirements: maintain a minimum cash balance of $41,153,000 at Dec-26; initial stakeholder payback expected in 47 months; revenue split between net interest income and fees from wealth and financial services.
Overall outlook: loans scale quickly, EBITDA rises to $2,327,000 by 2030 and liquidity remains strong.
Funding Requirements
We require $42,633,000 to cover 2026 capital expenditures and regulatory-quality cash to support a $36,000,000 deposit base and $34,500,000 loan portfolio; we project loans to reach $133,000,000 by 2030, EBITDA to grow from $11,000 to $2,327,000, ROE of 0.03, payback of 47 months, and a minimum year-end cash balance of $41,153,000.
Categories |
Amount, USD |
Branch Build-Out |
$450,000 |
Core Banking Software |
$280,000 |
Digital Banking Platform |
$180,000 |
Other CapEx (ATMs, security, furniture, equipment, vault, signage, network) |
$540,000 |
Planned subordinated debt (financing source) |
$2,000,000 |
Working capital |
$41,153,000 |
Total funding required |
$42,633,000 |